

The Hidden Labor-Supply Shock in Older Americans Leaving the Workforce
- Lingxiao Xu
- Aug 7
- 22 min read

The Hidden Labor-Supply Shock in Older Americans Leaving the Workforce
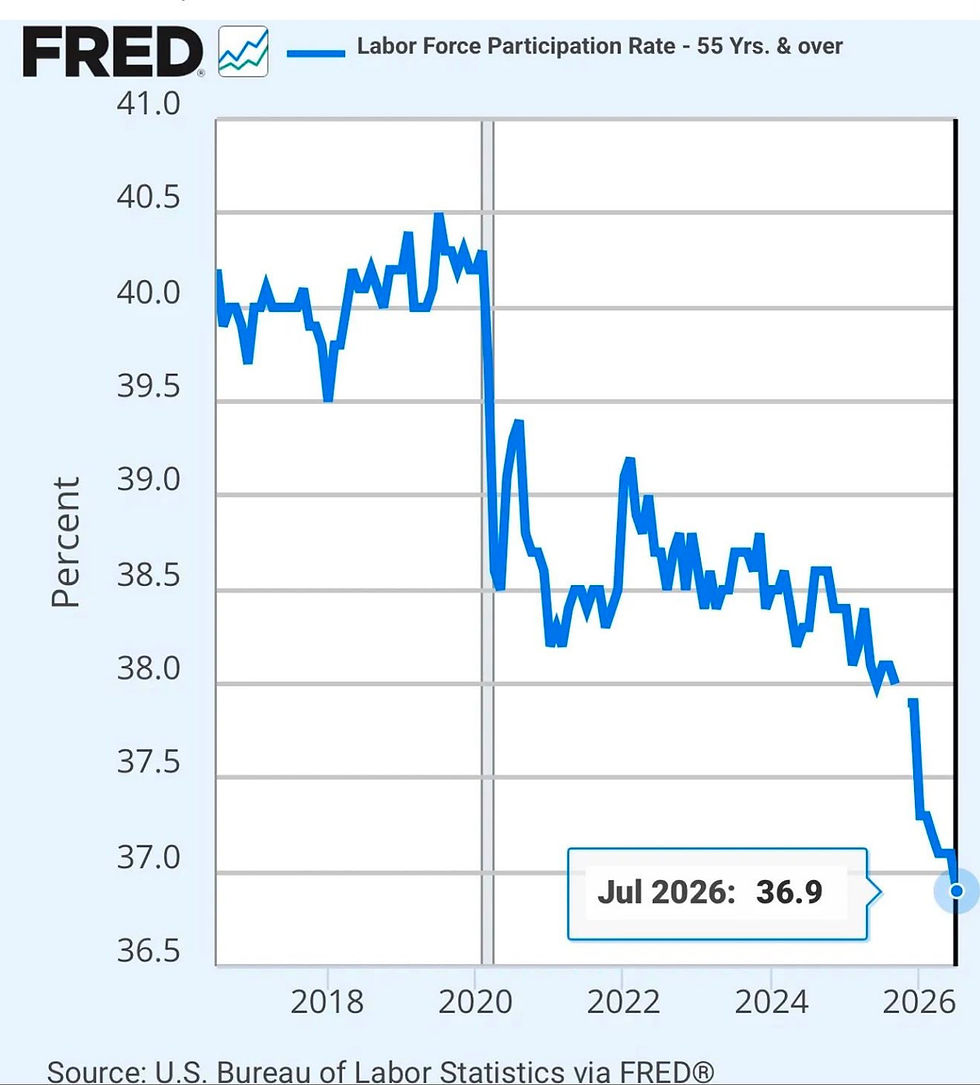
The most important labor-market signal is sometimes not the payroll number, the unemployment rate, or the wage print. It is the denominator. The July 2026 data show the labor-force participation rate for Americans aged 55 and older near 36.9%, down by more than a full percentage point over the past year. That is a large move for a demographic series that normally changes slowly. It is not just a retirement statistic. It is a macro signal about labor supply, household balance sheets, job-search frictions, and the way a softening labor market can coexist with persistent tightness in specific sectors.
The attached FRED chart makes the point visually. Participation among people 55 and over was near 40% before the pandemic. It fell sharply in 2020, partially recovered, then drifted lower again through 2024 and 2025 before breaking down further in 2026. July’s level is close to the bottom of the post-pandemic range. The source thesis is that this latest decline may reflect two forces working together: positive wealth effects that make retirement financially easier, and a weaker hiring environment that makes continued job search less attractive. That combination is more powerful than either force alone.
This is not simply a story about people becoming older. Demographic aging is the slow background. The recent move is too fast to attribute only to birthdays. A one-percentage-point decline in participation among such a large population group can represent hundreds of thousands of potential workers no longer offering labor. If the decline is sustained, it may lower the economy’s effective labor supply, keeping the labor market tighter than headline employment growth suggests. In other words, a weak hiring cycle can remove workers from the labor force rather than creating a clean rise in unemployment.
Why the 55+ Participation Rate Matters
The labor-force participation rate is the share of a population that is either employed or actively looking for work. For prime-age workers, participation usually reflects cyclical labor demand, childcare constraints, disability, education, immigration, and household income needs. For older workers, participation also reflects retirement wealth, health, Social Security claiming decisions, pension rules, spousal employment, asset-market conditions, and the personal value of leisure. The 55+ group is therefore not just another demographic bucket. It sits exactly at the boundary between labor-market economics and retirement economics.
That boundary matters because older workers are not uniformly marginal employees. Many have high firm-specific knowledge, supervisory experience, professional networks, client relationships, and tacit skills that are difficult to replace quickly. If some leave permanently, the loss is not measured only in headcount. It can reduce institutional memory, mentoring capacity, and the elasticity of labor supply in industries where experience is valuable. Healthcare, education, financial services, engineering, skilled trades, public administration, and professional services can all feel the exit of older workers in ways that are larger than their numerical share.
The July 2026 55+ participation reading must also be interpreted against the broader labor-market context. The overall participation rate has been falling, but prime-age participation remains comparatively resilient. That means the aggregate participation decline is not evenly distributed. If the weakness is concentrated among older workers and perhaps younger workers, the unemployment rate can become less informative. A person who leaves the labor force is not counted as unemployed. A falling unemployment rate can therefore be consistent with a weaker labor market if the labor force itself is shrinking.
The Participation Math
A small percentage-point move can matter because the base population is large. Suppose there are roughly 100 million Americans aged 55 and older. A one-percentage-point decline in participation would mean about one million fewer people either working or actively looking for work. The exact population base and survey definitions matter, but the order of magnitude is the point. In a labor market where monthly payroll growth has already slowed, a participation shock of this size can dominate the interpretation of labor slack.
This is why the participation rate belongs in the supply-side discussion. Labor-market tightness is not just demand for workers. It is demand relative to available supply. If job openings fall and payroll growth slows, investors may assume labor slack is rising. But if participation is falling at the same time, the increase in slack may be smaller than payrolls alone imply. The unemployment rate may not rise because some workers respond to weak hiring by leaving the search process. That is especially plausible for older workers, who have a credible nonemployment alternative: retirement.
There is also a measurement nuance. The household survey captures whether people are working or searching, while the establishment survey captures payroll jobs. When older workers exit the labor force, the effect can show up in participation before it shows up clearly in payroll composition. A person who quits searching after a layoff reduces labor supply immediately. A firm’s decision to replace that person, automate the role, delay hiring, or redistribute work may unfold over several quarters. This lag can make the labor market appear calm while supply is quietly adjusting.
Wealth Effects and the Retirement Decision
The first plausible driver is wealth. Record-high equity markets and rising household net worth can make retirement financially feasible earlier than planned. The life-cycle model of consumption and saving is the natural framework. Households accumulate assets during working years, then draw them down during retirement to smooth consumption over time. When financial wealth rises sharply, the household’s perceived lifetime resources increase. For a worker near retirement, that can change the trade-off between another year of work and the utility of leisure.
The effect is not evenly distributed. Older households own a disproportionate share of financial assets, retirement accounts, housing equity, and taxable portfolios. A rising equity market does not help every older worker equally, but it materially helps those with substantial 401(k), IRA, brokerage, pension, or home-equity buffers. For that group, a strong market can turn a tentative retirement plan into an executable one. The decision may not be framed as market timing. It may simply feel like the balance sheet is finally good enough.
A simple example helps. Imagine a 62-year-old worker with $900,000 in retirement assets who expects to retire when the portfolio reaches $1 million. A 12% market rally can push the portfolio beyond that threshold without any change in wage income. If the worker dislikes the current job, worries about layoffs, or sees few attractive openings elsewhere, the marginal value of continued employment falls. The worker may choose to retire not because work has become impossible, but because the option value of waiting has declined. Strong asset prices can make labor supply less elastic at exactly the moment the economy appears fragile.
Weak Hiring Changes the Search Calculation
The second force is weak hiring. The source note highlights a hiring rate below 4%, and the latest JOLTS data show a hires rate around 3.4% in June 2026. That is a low-mobility labor market. It does not necessarily mean layoffs are surging. It means fewer workers are being matched to new jobs. A low-hire, low-fire labor market can look superficially stable, but it is unpleasant for job seekers because the probability of finding a suitable new role declines.
Search-and-matching economics is useful here. In the Diamond-Mortensen-Pissarides framework, workers and firms need time and resources to find productive matches. The job-finding probability affects the value of unemployment and the reservation wage. If hiring is strong, an older worker who loses a job or dislikes a current role may search because the expected payoff is high. If hiring is weak, the expected duration of search rises. The worker faces more applications, more rejections, possible age discrimination, skill mismatch concerns, and the psychological cost of an uncertain process.
For someone near retirement, the search decision is especially asymmetric. A 35-year-old who spends six months searching still has decades of future earnings ahead. A 63-year-old may recover only a few years of wages even if the search succeeds. The present value of the search payoff is smaller, while the fixed cost of searching can be similar or higher. If severance, savings, Social Security eligibility, spousal income, or portfolio gains are available, retirement becomes the rational outside option. The weaker the hiring rate, the more attractive that outside option becomes.
Retirement as an Option, Not a Binary State
Retirement should be understood as an option with exercise conditions, not as a fixed age. Workers hold an option to continue working, reduce hours, switch jobs, consult, return part-time, or leave the labor force. The option is exercised when the value of work falls below the value of retirement, adjusted for uncertainty. Wealth increases the value of retirement. Weak hiring reduces the value of search. Health risks, caregiving responsibilities, commuting fatigue, workplace stress, and technology-driven role changes can further tilt the decision.
This option framework explains why participation can fall quickly. Many older workers may have been close to the retirement boundary already. They were still working because wages, benefits, routine, professional identity, or uncertainty about retirement finances kept them attached. When markets rise and hiring weakens, the boundary shifts. People who were previously marginally attached become retired. The series then moves not because millions suddenly changed preferences, but because many small individual thresholds were crossed at once.
It also explains why exits can be sticky. Once someone retires, returning is not costless. Skills can depreciate, networks can weaken, licensing can lapse, and employers may be reluctant to hire older applicants after a gap. Some retirees do return when inflation erodes purchasing power or portfolios decline, but the return flow is usually partial. The labor force can lose optional supply faster than it regains it. That asymmetry matters for macro forecasting because a temporary-looking participation drop may become a semi-permanent reduction in available labor.
The Role of Social Security, Pensions, and Health
Financial markets are only one part of the older-worker decision. Social Security claiming ages, Medicare eligibility, defined-benefit pension formulas, employer retiree benefits, and health status all matter. A worker between 62 and 67 can often claim Social Security, even if claiming early reduces monthly benefits. A worker at 65 gains Medicare eligibility. A worker with a traditional pension may face nonlinear incentives to retire once benefit formulas reach a plateau. These institutional thresholds can interact with market and hiring conditions.
Health also deserves attention. The pandemic changed work preferences and risk perceptions for some older workers. Even years later, health vulnerability, long-term illness, caregiving burdens, or a desire to protect household well-being can reduce labor-force attachment. Remote work made continued employment easier for some white-collar older workers, but not for everyone. In-person service, education, healthcare, manufacturing, transportation, and public-sector roles may still require physical presence. If job quality deteriorates or flexibility is limited, retirement becomes more attractive.
The key point is that the observed participation decline likely has multiple causes. Wealth effects and weak hiring are plausible immediate catalysts, but the underlying retirement option is embedded in a broader institutional and personal setting. This is why the move should not be dismissed as noise. When several retirement incentives align at the same time, the aggregate participation response can be abrupt. The chart is therefore less about one monthly datapoint than about a cluster of conditions pushing older workers toward the exit.
Why This Can Keep the Labor Market Tight
A decline in older-worker participation can keep the labor market tighter than payroll growth alone suggests. If labor demand slows and labor supply also shrinks, the net effect on wages and unemployment is ambiguous. Firms may post fewer openings, but still struggle to fill roles that require experience or reliability. The aggregate hiring rate can be low while certain employers remain constrained. This is the supply-side version of a labor-market slowdown: less churn, less entry, and less available experienced labor.
The Beveridge curve is a helpful reference. It relates job vacancies to unemployment. During periods of mismatch or reduced matching efficiency, vacancies can remain elevated relative to unemployment, or unemployment can fail to rise as much as expected when demand cools. Older-worker exits can contribute to this by reducing the pool of active searchers. The economy may look like it has fewer unemployed workers not because everyone is employed, but because some potential workers have stopped participating. This distinction matters for wage pressure.
Wage dynamics depend on who exits. If older workers leaving the labor force are high-wage workers, their exit may mechanically lower average wage measures in some sectors. But if they leave behind hard-to-fill roles, firms may need to pay more for replacements or invest in training. If they leave lower-wage physically demanding roles, employers may struggle with availability even without accelerating wages broadly. The distributional nature of the exit matters. A one-point participation decline can have very different consequences depending on which occupations and income cohorts are involved.
A Soft Labor Market Can Become a Supply Shock
The paradox is that labor-market weakness can create a supply shock. In a standard cyclical narrative, weak hiring raises unemployment and reduces wage pressure. But for older workers, weak hiring can push people into retirement, reducing the labor force. If those exits are persistent, the economy’s potential employment level falls. The same labor-market weakness that should create slack instead destroys some of the slack by reducing participation.
This mechanism is not unique to older workers, but it is strongest there because retirement is a legitimate alternative. Younger discouraged workers may return when conditions improve because they need decades of income. Older discouraged workers may not. Their search discouragement can become permanent retirement. That makes the 55+ participation rate an early warning indicator for the persistence of labor supply constraints. It tells us whether slack is accumulating inside the labor force or disappearing outside it.
From a macro perspective, this has implications for potential output. Potential GDP depends on labor input, capital input, and productivity. If labor input is lower because participation falls, the economy’s noninflationary growth speed may decline unless productivity accelerates. A smaller labor force can make moderate demand growth feel inflationary. This is why the participation shock belongs in the inflation debate, not just the retirement debate.
The Fed’s Problem: Weak Demand or Reduced Supply?
For monetary policy, the distinction is difficult. A weak payroll report and subdued hiring rate point to cooling demand. A falling older-worker participation rate points to reduced supply. If the Federal Reserve sees only demand weakness, it may lean toward easing. If it sees supply contraction, it must be more cautious because lower labor supply can keep wage pressure alive even when job growth slows. The policy signal becomes mixed.
The unemployment rate is less helpful when participation is moving. If the labor force shrinks, unemployment can fall or remain stable despite weak hiring. That can lead to a misleadingly benign reading of slack. A better approach is to examine participation by age group, employment-to-population ratios, job-finding rates, quits, hires, wage growth by industry, and the share of workers leaving the labor force after unemployment. The central bank needs to know whether workers are waiting on the sidelines or permanently retiring.
This is not an argument that the participation decline is automatically inflationary. If older workers leaving the labor force also reduce consumption sharply, demand could fall too. If productivity rises because firms automate, the supply loss could be offset. If immigration or prime-age participation improves, the aggregate labor supply hit could be moderated. The point is conditional: if demand remains resilient while older-worker participation keeps falling, the labor market can stay tighter than the headline payroll trend implies.
Asset Markets and the Feedback Loop
There is an interesting feedback loop between asset markets and labor supply. Rising equity prices can support retirement decisions by increasing household wealth. Those retirements can reduce labor supply. A tighter labor market can support wages and consumption, which can support earnings. But if labor supply becomes too constrained, wage pressure can keep inflation sticky and prevent the interest-rate relief that equity valuations expect. The same market rally that enables retirement can indirectly complicate the macro environment that justified the rally.
This feedback is especially relevant in an aging economy. Older households hold more wealth, and more workers sit near retirement thresholds. Asset-market gains therefore have a larger labor-supply effect than they would in a younger economy. A rally does not merely raise consumption through a standard wealth effect. It can also change the quantity of labor supplied. The labor supply curve for older workers may bend backward: higher wealth reduces the need to work, so labor supplied falls even if wages remain attractive.
For investors, this means equity-market strength is not purely a demand-side signal. It can be a labor-supply signal. When households near retirement see portfolios at records, their reservation conditions change. The macro effect depends on the size of the group and the permanence of exits. If only a small group retires earlier, the effect is manageable. If a broad cohort exits in a low-hiring environment, the economy may face a more binding labor constraint.
Why This Is Not Just Demographics
The obvious counterargument is that older-worker participation is supposed to fall because the population is aging. That is true in the slow-moving sense, but it does not fully explain a sharp one-year decline. Demographics change the level of participation gradually as people move into older age brackets. The current issue is the rate of change within the older population itself. A 56-year-old and a 72-year-old both sit inside the broad 55+ category, but their labor-force attachment is very different. If the composition within the group shifts toward older ages, participation should drift lower. But a sudden drop suggests something more cyclical or behavioral is also happening.
This distinction matters for forecasting. A purely demographic decline is predictable and can be built into long-run labor-supply estimates. A behaviorally induced retirement wave is less predictable and more sensitive to markets, hiring conditions, and expectations. If older workers are leaving because portfolios are strong and job search is unattractive, then the participation path can change quickly if equity markets fall, inflation rises, or hiring improves. Demographic aging is a slow tide. Participation decisions are a margin that can move in jumps.
The correct interpretation is therefore layered. Aging creates a larger pool of people near retirement. Asset gains and weak hiring change the incentives facing that pool. Institutional features such as Social Security and Medicare create thresholds. Health and caregiving needs add personal constraints. The observed participation drop is likely the result of these layers stacking on top of one another. That is exactly why it deserves market attention. When a slow structural force and a fast cyclical force point in the same direction, the outcome can surprise consensus forecasts.
The Household Balance-Sheet Channel
Household balance sheets transmit market prices into labor decisions. Economists often discuss wealth effects in terms of consumption: a higher stock market raises perceived wealth and can support spending. But wealth also affects labor supply. In the standard labor-leisure choice, a positive wealth shock can reduce desired labor if the income effect dominates the substitution effect. For older workers, the income effect can be especially strong because the remaining working horizon is short and retirement is already salient.
The wealth channel also operates through risk perception. A worker does not need to calculate a formal withdrawal rate to feel that retirement is safer. Rising account balances, higher home equity, and lower perceived probability of running out of money can reduce the fear of leaving work. Conversely, a weak labor market increases the fear that searching will be long and unpleasant. The combined message is powerful: assets say retirement is affordable, while hiring conditions say continued attachment is costly. The rational response for many is to stop searching and preserve time.
There is a distributional caveat. Many older Americans are not wealthy enough to retire comfortably. Some may need to keep working because savings are inadequate, healthcare costs are high, or housing expenses remain burdensome. But participation rates are averages across heterogeneous households. If asset-rich older workers retire earlier while asset-poor older workers try to keep working, the aggregate still falls if the first group is large enough or responds more strongly. This heterogeneity also means the macro signal can coexist with household stress. Early retirement for one group can occur alongside involuntary nonparticipation for another.
Age, Skill, and the Productivity Question
Older-worker exits have an ambiguous relationship with productivity. In some roles, older workers are less physically able or less attached to new technologies, and replacement by younger workers or automation can raise productivity. In other roles, experience is itself a productivity asset. Senior nurses, teachers, engineers, technicians, managers, traders, accountants, and client-facing professionals often carry knowledge that is not fully codified. Their exit can create gaps that are hard to fill with entry-level hiring.
The productivity effect depends on whether firms respond with substitution or simplification. A firm can substitute capital for labor, redesign workflows, outsource tasks, or promote younger workers. If the response is successful, a smaller labor force need not reduce output much. If the response is poor, service quality declines, errors rise, training burdens increase, and bottlenecks appear. The same participation decline can therefore either accelerate productivity-enhancing restructuring or expose the fragility of organizations that depended on tacit knowledge.
This is important for inflation. If older-worker exits are offset by productivity gains, the supply shock is smaller. If exits reduce effective capacity, inflation pressure can persist even with slower employment growth. Service sectors are particularly relevant because they are labor intensive and often experience-dependent. A manufacturing firm may automate a process; a hospital, school, or advisory business may find that replacing experienced workers is much harder. The inflation implication is therefore sectoral, not uniform.
The Low-Hire, Low-Fire Labor Market
The current labor market increasingly resembles a low-hire, low-fire equilibrium. Layoffs are not necessarily explosive, but hiring is subdued. This environment changes worker behavior. When firms are reluctant to hire, employed workers become less willing to quit, unemployed workers face longer searches, and marginal workers become more likely to exit. Labor-market cooling therefore shows up less as a dramatic unemployment spike and more as reduced mobility. That is a different kind of weakness from the traditional recession playbook.
Older workers are especially exposed to this equilibrium because job matching is more fragile late in a career. Employers may worry about tenure, salary expectations, health costs, adaptability, or retirement timing. Some of those concerns are stereotypes, but stereotypes can still affect search outcomes. A low hiring rate magnifies them because employers can be more selective. The result is a lower expected return to search for older applicants, even if they are highly capable.
This can create a hidden discouragement effect. A worker may not report being discouraged in a dramatic way. He may simply decide that the search is not worth it, that consulting is enough, or that retirement starts now. In the aggregate data, that looks like nonparticipation. In lived experience, it looks like a quiet decision to stop fighting a market that no longer seems to offer attractive matches. This is why participation can decline without a proportional rise in measured unemployment.
Implications for Corporate Labor Strategy
Companies should not read older-worker exits as a purely macro issue. They affect workforce planning. If experienced employees are closer to retirement than managers assume, firms need succession plans, knowledge transfer systems, flexible work arrangements, and phased-retirement options. A company that ignores the participation signal may discover that key expertise leaves faster than it can be replaced. The labor-market risk is not just wage inflation; it is operational continuity.
Phased retirement can be a useful response. Many older workers may not want full-time employment but may be willing to work part-time, mentor, consult, or handle specific projects. Firms that offer flexible arrangements can retain some experience even as formal participation falls. This is a private-sector way to soften the macro supply shock. It also highlights the difference between headcount and labor input. A worker who leaves full-time employment but remains available part-time is not equivalent to a worker who disappears completely.
Technology investment is another response, but it must be realistic. Automation can replace tasks, not all judgment. Artificial intelligence can help document procedures, summarize workflows, and augment less experienced workers, but it cannot instantly replicate every form of tacit knowledge. The best firms will use technology to leverage remaining experienced workers, not simply to assume that their exits are costless. In a tight experienced-labor market, the return on knowledge management rises.
Policy and Long-Run Growth
At the policy level, lower older-worker participation raises questions about long-run growth. An aging society can maintain growth through higher productivity, higher prime-age participation, immigration, later retirement, or higher capital intensity. If older workers leave earlier while immigration is constrained and productivity gains are uneven, potential growth falls. That does not create an immediate crisis, but it changes the economy’s speed limit. Demand that would have been sustainable with a larger labor force can become inflationary with a smaller one.
Policy can influence the margin. Tax rules, Social Security earnings tests, Medicare design, disability policy, retraining programs, and anti-age-discrimination enforcement can all affect older-worker participation. So can infrastructure around caregiving and flexible work. The goal should not be to force older Americans to work. It should be to reduce unnecessary barriers for those who want to remain attached. A labor market that loses willing experienced workers because search is inefficient or jobs are inflexible is leaving output on the table.
This is also a retirement-security issue. If some workers retire because they are wealthy, the macro story is benign for them. If others retire because searching is too hard despite inadequate savings, the social story is less benign. Over time, early exits by financially fragile households can increase dependence on public programs or family support. The same participation statistic therefore carries both a macro supply message and a household vulnerability message.
Scenario Map
There are three broad scenarios. In the benign scenario, older-worker participation stabilizes, hiring improves modestly, and wealth effects do not trigger a much larger retirement wave. Payroll growth slows but does not collapse, wage growth cools, and the Fed can interpret the labor market as gradually rebalancing. In that world, the July decline is important but not regime-changing. It becomes a warning about the retirement margin rather than a durable supply shock.
In the supply-constrained scenario, participation keeps falling while demand remains resilient. Firms continue to need experienced workers, but the pool shrinks. Wage pressure persists in service and skill-intensive sectors. Inflation declines only slowly, and the Fed finds it difficult to ease aggressively. Long-duration assets then face a less friendly mix: weaker headline employment but less disinflation than expected. This is the scenario in which the participation denominator matters most.
In the weak-demand scenario, participation falls because households and workers become broadly discouraged, while consumption also weakens. Retirements are not only wealth-enabled; some are defensive exits from a poor labor market. In that world, lower participation does not keep the market tight for long because demand deteriorates too. Rates fall, credit risk rises, and equity leadership narrows. The key difference between this and the supply-constrained scenario is consumption. If retirees keep spending from wealth, demand holds. If they cut spending, the labor-supply story becomes part of a broader slowdown.
Historical Echoes and the Post-Pandemic Difference
The pandemic retirement wave is the obvious historical comparison, but the current decline is different in composition and meaning. In 2020, many older workers left because the health shock was immediate, workplaces were disrupted, and asset prices recovered quickly after an initial crash. That episode combined fear, policy support, household cash buffers, and a sudden reconsideration of work. The 2026 decline is less dramatic on the surface, but it may be more revealing because it is occurring without the same emergency context. A participation drop during a public-health shock can be treated as extraordinary. A participation drop during a mature expansion with record asset prices and weak hiring may say more about the new steady state.
The post-pandemic difference is that labor-market attachment has become more conditional. Remote work, hybrid work, portfolio wealth, health preferences, caregiving realities, and age-specific job-search frictions have changed the practical calculus. Older workers may remain attached when the job is flexible, the match is good, and compensation is high. They may leave quickly when flexibility disappears or the search environment worsens. This suggests that the 55+ labor supply curve may be more kinked than before. It is not simply lower; it may respond more abruptly to changes in wealth and job quality.
The 1970s and early 1980s offer another contrast. Then, high inflation and weaker real wealth often forced older households to remain attached longer or return to work. Today, asset wealth has helped some retire, even as inflation has squeezed others. The result is a bifurcated older-worker economy. Wealthier households experience retirement as an option. Less wealthy households experience nonparticipation as vulnerability. Macro data average these stories together, which can hide distributional stress. A falling participation rate can therefore be both a sign of financial comfort for some and labor-market discouragement for others.
This historical framing matters because it cautions against a single narrative. The decline is not simply voluntary early retirement, nor simply weak labor demand, nor simply aging. It is a regime interaction. The aging population creates the eligible pool. Asset markets finance exits. Weak hiring lowers the reward to search. Institutions define the thresholds. Health and work preferences influence the final decision. When these factors line up, the participation rate can move like a cyclical variable even though retirement is usually treated as structural.
A Simple Macro Accounting Framework
A useful accounting identity is employment equals population times participation times one minus unemployment. For the 55+ group, the participation term is now doing much of the work. If population rises because the cohort is growing, but participation falls, the contribution to employment can stagnate or decline. That means demographic growth alone does not guarantee labor supply growth. The participation decision is the key margin.
At the whole-economy level, labor input can be written approximately as population multiplied by participation, employment probability, average hours, and productivity per hour. A decline in 55+ participation reduces one component of labor input. It can be offset by more prime-age participation, more immigration, longer hours, or higher productivity. But if those offsets do not arrive, potential output is lower. This is why a participation-rate chart can be as important as a payroll chart. Payrolls tell us how many jobs were created. Participation tells us how many people are available to fill jobs.
The same identity clarifies why the unemployment rate can mislead. If participation falls, the labor force shrinks. A smaller labor force can mechanically hold down unemployment even when employment is weak. The policy question is whether nonparticipants are available at the right wage and conditions. If they are available, the economy has hidden slack. If they are truly retired, the slack is gone. The 55+ participation decline matters because retirement is one of the clearest cases where nonparticipation may be permanent rather than merely hidden.
Investors should therefore treat the participation rate as an input into estimates of the output gap. A conventional output gap model that assumes labor supply is stable may overestimate slack when older-worker exits accelerate. That can lead to mistaken conclusions about inflation, margins, and interest rates. The chart is not a demographic curiosity. It is a parameter update for the economy’s supply side.
The timing also makes the signal more consequential. A participation decline in a booming hiring market might be reversed quickly as employers bid workers back. A participation decline in a low-hiring market is more likely to harden into retirement because workers do not see enough attractive matches to justify waiting. That is the core asymmetry. The same one-point decline means more when the matching function is weak.
Market Implications
For rates markets, declining older-worker participation creates a two-sided interpretation. On one hand, weaker hiring and lower participation can signal slower growth, supporting lower yields. On the other hand, if participation declines represent a structural labor-supply reduction, the economy’s inflation threshold may be lower, supporting a higher real-rate or term-premium risk. The curve response depends on whether investors price the data as cyclical weakness or supply-side tightness.
For equities, the signal is also mixed. A wealth-driven retirement wave can reflect strong household balance sheets and high asset prices, which are supportive for consumption and risk appetite. But a shrinking experienced labor force can pressure margins in labor-intensive sectors, worsen service bottlenecks, and accelerate wage competition for specialized roles. Companies with automation capacity, scalable software, and low labor intensity may benefit relative to firms dependent on scarce experienced workers.
For credit, the key issue is income stability. If older workers retire with adequate wealth, consumer credit stress may not rise. If workers retire because job search is unattractive but balance sheets are only marginal, household cash flows may deteriorate over time. That distinction matters for consumer lenders, healthcare spending, housing turnover, and retirement-income products. The same participation decline can be benign for affluent households and stressful for households with thin savings.
What to Watch Next
The first indicator is whether the 55+ participation decline continues over the next several releases. One month can be noisy; a multi-month trend is harder to dismiss. The second is the gap between prime-age participation and older-worker participation. If prime-age participation remains firm while older participation falls, the story is specifically about retirement and demographic margins rather than broad discouragement.
The third indicator is hiring. If the hires rate remains near the mid-3% range, older workers who lose jobs or want to change roles will face a weak search environment. The fourth is job openings by industry and wage growth by occupation. A broad decline in openings would support a demand slowdown story; persistent openings in experience-heavy sectors would support a supply-constraint story. The fifth is household wealth. If equity and housing prices remain elevated, retirement wealth effects may persist.
The sixth indicator is reentry. If older workers leave participation but later return as consultants, part-time workers, or gig workers, the supply loss is softer. If exits are permanent, the shock is larger. The seventh is Social Security and retirement claiming behavior. A rise in claiming or pension take-up would confirm that labor-force exits are becoming formal retirements rather than temporary pauses. These indicators together will tell us whether the July decline is a warning shot or the start of a structural adjustment.
Conclusion: The Denominator Is the Story
The decline in labor-force participation among Americans aged 55 and older is large enough to matter. It is comparable in magnitude to the pandemic-era shock, and the July 2026 reading near 36.9% sits at a troubling low. The most plausible explanation is not one force but the interaction of several: strong asset markets and household wealth make retirement easier, weak hiring makes job search less appealing, and older workers near retirement have a credible alternative to continued labor-force attachment.
If sustained, this is a structural labor-supply issue. It can keep the labor market tighter than payroll growth alone suggests, mute the rise in unemployment, complicate wage interpretation, and make the Federal Reserve’s job harder. Weak hiring would normally create slack. But when weak hiring pushes older workers into retirement, some of that slack disappears from the measured labor force. The economy then looks softer and tighter at the same time.
The practical takeaway is simple: do not analyze the labor market only through job creation. Watch participation, especially among older workers. Watch hiring rates and job-finding probabilities. Watch wealth effects and retirement thresholds. The denominator is moving, and when the denominator moves, every headline labor statistic changes meaning. The 55+ participation decline is not a side note. It is one of the clearest signs that the post-pandemic labor market is still being reshaped by wealth, demographics, and search frictions.


Comments